Viewing as
Teaching this? The teacher view adds 2 files, the mark schemes and the model answers.
Business · Putting a business idea into practice
Cash and cash flow forecasting
A business can be profitable and still fail if it runs out of cash. This lesson explains why cash matters, how it differs from profit, and how to calculate and read a cash-flow forecast.
Last Lesson
Answer from memory before the answers appear.
-
What is break-even?
The point where total revenue equals total costs.
-
How do you calculate break-even output?
Fixed costs ÷ (sales price - variable cost per unit).
-
What is the margin of safety?
Actual sales - break-even output.
-
What happens to break-even if fixed costs rise?
It rises - more units must be sold.
Learning Objectives
- 1Explain the importance of cash to a business.
- 2Explain the difference between cash and profit.
- 3Explain cash inflows, cash outflows and net cash flow.
- 4Calculate opening and closing balances in a cash-flow forecast.
- 5Interpret a cash-flow forecast.
THE BIG IDEA
Profit keeps a business going in the long run. Cash keeps it alive this week.
More businesses fail because they run out of cash than because they never make a profit.
Why Cash Matters
Cash is the money a business has available to spend right now - in the bank or in the till.
-
To pay suppliers
Without cash, suppliers stop delivering stock and materials, and the business cannot sell anything.
-
To pay overheads
Rent, electricity and insurance must be paid on time, or the business may lose its premises.
-
To pay employees
Staff expect to be paid on time; if they are not, they may leave.
-
To prevent business failure
A business that cannot pay its debts when they are due is insolvent, and may be forced to close - even if it is profitable on paper.
Watching the Bank Balance
Small business owners check their cash constantly, because the bills never stop: suppliers, rent, wages. A cash-flow forecast lets them see a problem coming months before it arrives, while there is still time to do something about it.
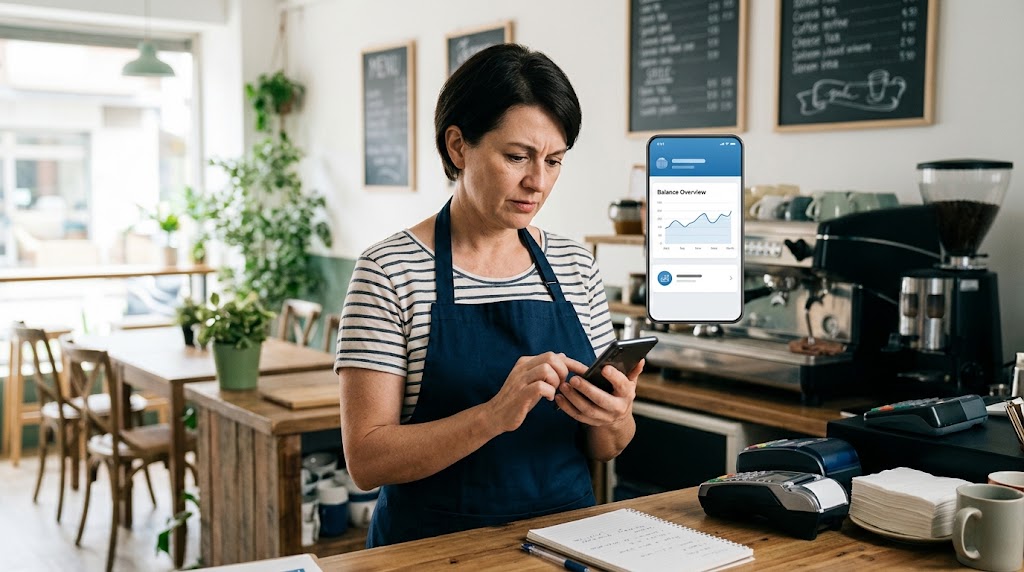
Knowing how much cash there is - and will be - is part of the daily job.
Cash or Profit?
Cash
- The money the business actually has right now.
- Needed to pay bills when they are due.
- Changes the moment money comes in or goes out.
- Short term: without it, a business can fail this month.
Profit
- Revenue minus costs over a period of time.
- Includes sales that customers have not yet paid for.
- Worked out at the end of a period.
- Long term: without it, a business cannot survive for ever.
How a Profitable Business Runs Out of Cash
Profit counts a sale when it is made; cash counts it when the money arrives.
-
Customers pay late
A business that lets customers pay in 60 days has made the sale, and the profit, but has none of the cash yet.
-
Paying for stock up front
A toy shop buys its Christmas stock in September, months before customers buy it.
-
Buying equipment
A large purchase such as a van uses up cash immediately, even though it will earn money for years.
-
Growing too fast
More orders mean more materials and staff to pay for before the customers pay.
The Parts of a Cash-Flow Forecast
-
Cash inflows
Money coming into the business: cash sales, payments from customers, loans, and money invested by the owner.
-
Cash outflows
Money going out of the business: stock, wages, rent, bills and loan repayments.
-
Net cash flow
Cash inflows - cash outflows. Negative if more goes out than comes in.
-
Opening balance
The cash the business has at the start of the month. It is always last month's closing balance.
-
Closing balance
Opening balance + net cash flow. The cash left at the end of the month.
The Café's Cash-Flow Forecast
-
Cash inflows: sales
January (£): 5,000. February (£): 6,000. March (£): 7,500
-
Rent
January (£): 1,500. February (£): 1,500. March (£): 1,500
-
Wages
January (£): 3,000. February (£): 2,500. March (£): 3,000
-
Stock
January (£): 2,000. February (£): 1,000. March (£): 1,000
-
Total cash outflows
January (£): 6,500. February (£): 5,000. March (£): 5,500
-
Net cash flow
January (£): (1,500). February (£): 1,000. March (£): 2,000
-
Opening balance
January (£): 2,000. February (£): 500. March (£): 1,500
-
Closing balance
January (£): 500. February (£): 1,500. March (£): 3,500
Working Through January
Always work in this order.
Using the café's forecast, show how January's closing balance is calculated, and why it becomes February's opening balance.
- 1 Total cash outflows £1,500 + £3,000 + £2,000 = £6,500
- 2 Net cash flow £5,000 - £6,500 = (£1,500)
- 3 Closing balance £2,000 + (£1,500) = £500
- 4 Carry it forward January's closing balance of £500 becomes February's opening balance
AnswerJanuary closing balance = £500
Reading the Forecast
What the café's owner can learn from it.
-
A difficult January
More cash goes out than comes in, and the balance falls to just £500 - dangerously low if a bill is bigger than expected.
-
Recovery
Net cash flow is positive in February and March, so the balance rises to £3,500.
-
Planning ahead
Knowing January will be tight, the owner could arrange an overdraft in advance, delay buying stock, or run a promotion to boost sales.
-
A forecast, not a fact
The figures are predictions; if sales are lower than forecast, the cash could run out.
Why Businesses Use Cash-Flow Forecasts
A forecast is an early warning system.
-
Spot shortages early
See months ahead when cash may run low, and arrange finance before it is needed.
-
Plan spending
Choose the best time to buy equipment or stock.
-
Get a loan
Banks usually ask for a cash-flow forecast before lending to a new business.
-
Compare and control
Compare actual cash flow with the forecast and act if they differ.
Case study
Carillion: Profitable on Paper, Out of Cash
Carillion was one of Britain's biggest construction and services companies, building hospitals and roads and employing around 43,000 people. It reported a profit for 2016, but it was waiting months to be paid on many of its contracts while still having to pay its staff and suppliers, and it had built up huge debts. When it could no longer find the cash to pay what it owed, it went into liquidation in January 2018. Carillion showed that profit on paper is not the same as cash in the bank.
Complete the Forecast
A bike repair shop starts April with £800. April inflows are £3,000 and outflows £3,600. May inflows are £4,200 and outflows £3,400. June inflows are £2,500 and outflows £3,900. Draw a cash-flow forecast, calculate the net cash flow and closing balance for each month, and say which month the owner should worry about.
1. Draw the table with three month columns.
2. Calculate net cash flow each month.
3. Calculate the closing balance and carry it forward.
4. Name the problem month and suggest one solution.
A good answer shows: Net cash flows of (£600), £800 and (£1,400); closing balances of £200, £1,000 and (£400). June needs action because the balance goes negative.
Can I...?
- 1Explain why cash matters to a business.
- 2Explain the difference between cash and profit.
- 3Explain how a profitable business can run out of cash.
- 4Explain cash inflows and outflows.
- 5Calculate net cash flow.
- 6Calculate opening and closing balances.
- 7Interpret a cash-flow forecast.
Summary & Exam Focus
- Cash is needed to pay suppliers, overheads and employees, and to avoid insolvency.
- Cash is money available now; profit is revenue minus costs over a period.
- Net cash flow = inflows - outflows; closing balance = opening balance + net cash flow.
- A cash-flow forecast warns of shortages so the business can act in time.
Exam focus
Explain one reason why a business might be profitable but still run out of cash. (3 marks) (3 marks)
Use the difference in timing: the sale, and the profit, are counted when the goods are sold, but the cash only arrives when the customer pays.
Key terms
The vocabulary this lesson expects you to use. Each one is linked from the first place it appears above.
- Cash
- Money a business has available to spend immediately, in the bank or in the till.
- Cash flow
- The movement of cash into and out of a business.
- Cash inflows
- Money coming into a business, such as cash sales and loans.
- Cash outflows
- Money going out of a business, such as wages, rent and stock.
- Net cash flow
- Cash inflows minus cash outflows.
- Opening balance
- The cash a business has at the start of a period - last period's closing balance.
- Closing balance
- Opening balance plus net cash flow.
- Insolvency
- When a business cannot pay its debts when they are due.
- Cash-flow forecast
- A prediction of a business's cash inflows and outflows over future months.
Downloads
Free to keep, print and annotate.
- Cash and cash flow forecasting.pptx Built from the lesson script on 25 September 2026. View
- Cash and cash flow forecasting - Completed Notes.docx The full notes for the lesson, to revise from. Built from the lesson script on 25 September 2026. View
- Cash and cash flow forecasting - Exam Questions.docx Built from the lesson script on 25 September 2026. View
Something here looks wrong?
Tell us what and we will go and look. It goes to whoever writes these pages, nobody else, and we do not ask who you are — so there is nothing to sign and nothing comes back to you.